


Investment Committee Deck Feedback From Institutional Investors
Investment committee feedback usually reflects missing evidence, unclear economics, or unsupported assumptions in a specific deck section. Sponsors can reduce deferrals and resubmission requests by tracing each headline claim to the capital stack, projections, track record, risk mitigants, and near-final governance documents before submission.
The full architecture of a committee-ready deck is covered in the guide to what an investment committee deck must include. This article focuses on the feedback layer: what reviewers actually flag after a deck lands on their desk, and what those flags mean for the sponsor.
Key principle: IC feedback arrives in one of three forms. A pass is a final rejection with no path forward at that firm. A deferral means the opportunity is held pending additional information or a future cycle. A resubmission request means the reviewer sees merit but the deck has specific structural problems that must be corrected before committee review can proceed. Each outcome maps to different types of deck failures.
Why Sponsors Rarely Hear the Real Reason
Institutional reviewers seldom deliver detailed written feedback after a pass. The analyst who screened the deck moves to the next deal. The LP's internal process does not require a sponsor debrief. What the sponsor receives, if anything, is a brief note: "does not fit our current mandate" or "we are fully deployed in this asset class."
The cause is almost always one of the following: a section of the deck failed to answer the question the reviewer was asking at that stage, or the deck contained a structural inconsistency that triggered a credibility concern before the opportunity was fully evaluated.
Understanding the difference between mandate fit and deck failure matters. Deck quality failures are fixable. Sponsors who treat every rejection as a mandate issue never identify the structural weaknesses that follow them from one submission to the next.
The Capital Raise Pre-Flight is IRC Partners' fixed-fee diagnostic that scores a raise against the same twelve institutional gates a deal must clear before IRC Partners takes it into a strategic partnership.
Feedback by Deck Section: What Reviewers Flag and Why
Each section of an IC deck generates its own category of reviewer feedback. The table below maps the most common flags to the deck section that produces them and the underlying structural problem each flag signals.
Executive Summary Flags
The executive summary is the first section a reviewer reads and the one most likely to determine whether the rest of the deck gets evaluated at all. The most common flag is an incomplete ask: the reviewer cannot determine the raise amount, the LP equity percentage, the target net IRR, and the hold period from the first slide alone.
A second common flag is a mismatch between the headline return and the capital structure. If the executive summary shows a 16% net IRR but the capital stack section later reveals a leverage band that does not support that return at current debt costs, the reviewer flags the inconsistency and the deck loses credibility before the financial section is reached.
Investment Thesis Flags
A committee-ready thesis explains why this specific site, at this specific basis, with this specific business plan, produces a return that is structurally unique to this opportunity.
The distinction matters because the investment committee is evaluating manager judgment. A thesis that any developer could write does not demonstrate that this sponsor has an edge worth allocating to.
Capital Stack and Projection Flags
These two sections generate the highest volume of resubmission requests. Capital stack flags typically involve one of three problems: the LTV assumption is stated without a committed term sheet, the debt cost assumption does not reflect current market conditions, or the equity split between GP and LP is described without reference to a signed or near-final term sheet.
Projection flags follow a consistent pattern. Reviewers flag gross IRR presented without net IRR, because LPs underwrite what they actually earn after fees and carry. The ILPA Reporting Template sets the standard institutional LPs use when evaluating whether a sponsor's performance reporting is structured for professional review. They flag projections with no downside scenario, because a model that only shows the base case signals that the assumptions have not been pressure-tested. The financial projections institutional LPs expect in a pitch deck follow a three-slide structure: return summary, assumptions, and scenario analysis. Decks that compress all three into a single slide generate follow-up questions that slow the process.
Track Record Flags
Track record is the section where institutional reviewers apply the most scrutiny and where sponsors most often present information in a way that creates more questions than it answers. The two most common flags are attribution and verification.
Attribution means that the returns shown in the deck are tied to deals the current team executed in their current roles, with capital they raised and managed. Returns from prior employers, returns from deals where the sponsor was a minority partner, and returns from deals that closed under different market conditions all require clear disclosure. Reviewers flag track records that blend attributed and unattributed performance without distinguishing between them.
Verification means the returns are presented with enough deal-level detail that an LP's consultant can confirm them. A summary table showing aggregate IRR across a portfolio is a starting point. A deal-by-deal schedule showing asset name, vintage, strategy, gross IRR, net IRR, and current status is what survives diligence.
Risk and Governance Flags
Risk section flags are almost always the same: the sponsor listed risks without pairing each one with a specific mitigation. A risk section that names construction cost overrun, lease-up delay, and exit cap rate expansion as risks, and then provides no mitigation for any of them, reads as a compliance checkbox with no analytical value.
Governance flags arise when the deck describes terms that do not yet exist in executed documents. A deck that references a signed operating agreement with specific approval thresholds is describing a documented structure. Committee review proceeds when governance terms appear in signed or near-final documents. SEC guidance for private fund advisers sets out the disclosure and documentation standards that apply to private fund advisers operating under SEC oversight.
The difference between a pitch deck and an IC deck is the level of document completeness the committee expects. The key differences between a pitch deck and an IC deck clarify exactly where that line sits and what the IC deck must contain that the pitch deck does not.
{{main-cta}}
How to Use This Feedback Map Before Submission
The section-by-section feedback map above is a self-audit tool. Before submitting to any institutional LP, a sponsor can run the deck against each flag category and identify which sections are generating potential objections.
A practical pre-submission audit follows this sequence:
- Executive summary audit. Confirm that a reader with no prior knowledge of the deal can extract the raise amount, LP equity percentage, target net IRR, hold period, and asset class from the first slide alone. If any of those elements require reading further into the deck, the summary is incomplete.
- Thesis specificity check. Replace the thesis with a one-sentence version: "This deal produces [X% net IRR] because [specific edge or structural advantage], which a comparable asset in the same market cannot replicate because [reason]." A thesis that requires revision before submission will fail that test on the current language.
- Number trace. Pick five figures from the executive summary and trace each one through the financial model, the sources and uses statement, and the operating agreement draft. Every figure must match exactly. A mismatch anywhere is a committee flag.
- Projection completeness check. Confirm the deck shows gross IRR and net IRR side by side, equity multiple, hold period, leverage band, and at least one downside scenario. If any element is missing, the projection section is incomplete for institutional review.
- Track record attribution check. For each deal in the track record, confirm that the attribution is clear: which members of the current team executed the deal, in what role, and with what capital. Any deal that does not meet that standard requires a disclosure note.
- Risk-to-mitigation pairing. For every risk named in the risk section, confirm that a specific mitigation is paired with it. A risk with no mitigation is a flag. Vague mitigations ("we will monitor market conditions") carry the same weight as a blank field.
- Governance document check. Confirm that every governance term described in the deck appears in a signed or near-final operating agreement.
Key takeaway: A deck that clears all seven of these checks before submission is a deck that has eliminated the most common categories of reviewer feedback. The goal is to reach the committee with no open questions that the deck itself should have answered.
Frequently Asked Questions
What is the difference between a pass and a deferral from an institutional LP?
A pass means the LP has reviewed the opportunity and closed it at their firm. There is no path forward with that allocator for that deal. A deferral means the LP sees potential merit but the timing, mandate fit, or deck completeness does not support a committee submission at that moment. Deferrals often come with a specific condition: resubmit when the debt stack is committed, or return in the next fund cycle. Sponsors should confirm in writing which outcome they received, because the two require different follow-up strategies.
Why do institutional reviewers flag gross IRR instead of asking for net IRR separately?
Reviewers flag gross-only presentations because the gap between gross and net IRR is where fee drag and carry impact are hidden. An institutional LP's investment committee compares funds on net returns. A deck that leads with gross IRR forces the LP to calculate net IRR themselves, which creates friction and signals that the sponsor has not structured the presentation for institutional review.
What does "attribution unclear" mean in track record feedback?
It means the reviewer cannot determine which members of the current team executed the deals listed, in what capacity, and with what level of decision-making authority. Returns earned at a prior employer, as a passive co-investor, or in a role that did not include capital raising or asset management do not carry the same weight as returns earned by the current team in their current structure. Reviewers flag blended track records that do not distinguish between these categories.
How specific does a risk mitigation need to be to satisfy an institutional reviewer?
The mitigation must be specific enough to answer the question: "If this risk materializes, what has the sponsor already done or committed to do?" A mitigation that says "we will adjust the business plan as needed" answers nothing. A mitigation that says "construction cost overrun risk is addressed through a 10% contingency reserve in the sources and uses, a fixed-price contract with [contractor type], and a draw schedule reviewed by the lender's inspector" is specific enough to survive committee review.
Can a sponsor resubmit to the same LP after a pass?
A pass from an institutional LP is generally final for that deal. Resubmission on the same opportunity, with the same structure, is viewed as a failure to understand the feedback. Resubmission on a different deal, after a demonstrated period of relationship building and structural improvement, is a different matter. Sponsors who receive a pass should ask directly whether the LP would consider a future submission on a different deal before assuming the relationship is closed.
What governance terms are most commonly flagged as incomplete at the IC stage?
The four most commonly flagged governance terms are: approval thresholds for major capital decisions, key person provisions and succession protocols, conflict of interest disclosure procedures, and LP reporting schedules with specific content requirements. Decks that describe these terms in general language without referencing a signed or near-final operating agreement generate governance flags.
What is the institutional readiness score threshold for a committee-ready deck?
The Institutional Readiness Score runs from 0 to 100. A score of 85 or above is the threshold IRC Partners uses to assess whether a deck and supporting materials are structurally ready for committee submission. Scores below 85 indicate that one or more of the twelve institutional gates has a structural weakness that reviewers are likely to flag.
Continue reading this series:
- 5 LP Financial Exhibits for Real Estate Pitch Decks
- Inside Institutional Due Diligence: The Sequence Investors Run From First Meeting to Wire
- Real Estate Investment Returns: What $10M+ Sponsors Must Show Institutional LPs
The Capital Raise Pre-Flight is IRC Partners’ fixed-fee diagnostic that scores a raise against the same twelve institutional gates a deal must clear before IRC Partners takes it into a strategic partnership. It is where every engagement begins, whether you are pre-revenue building toward a first institutional round or scaling a company that has raised before. For deals that clear, the full strategic partnership follows. IRC Partners advises operators raising $5M to $250M of institutional capital. If you are taking a raise to market, start here.
Need guidance on your capital raise?


Shortlist of Debt Advisory and Venture Debt Advisors
Fees for Debt Advisory and Venture Debt
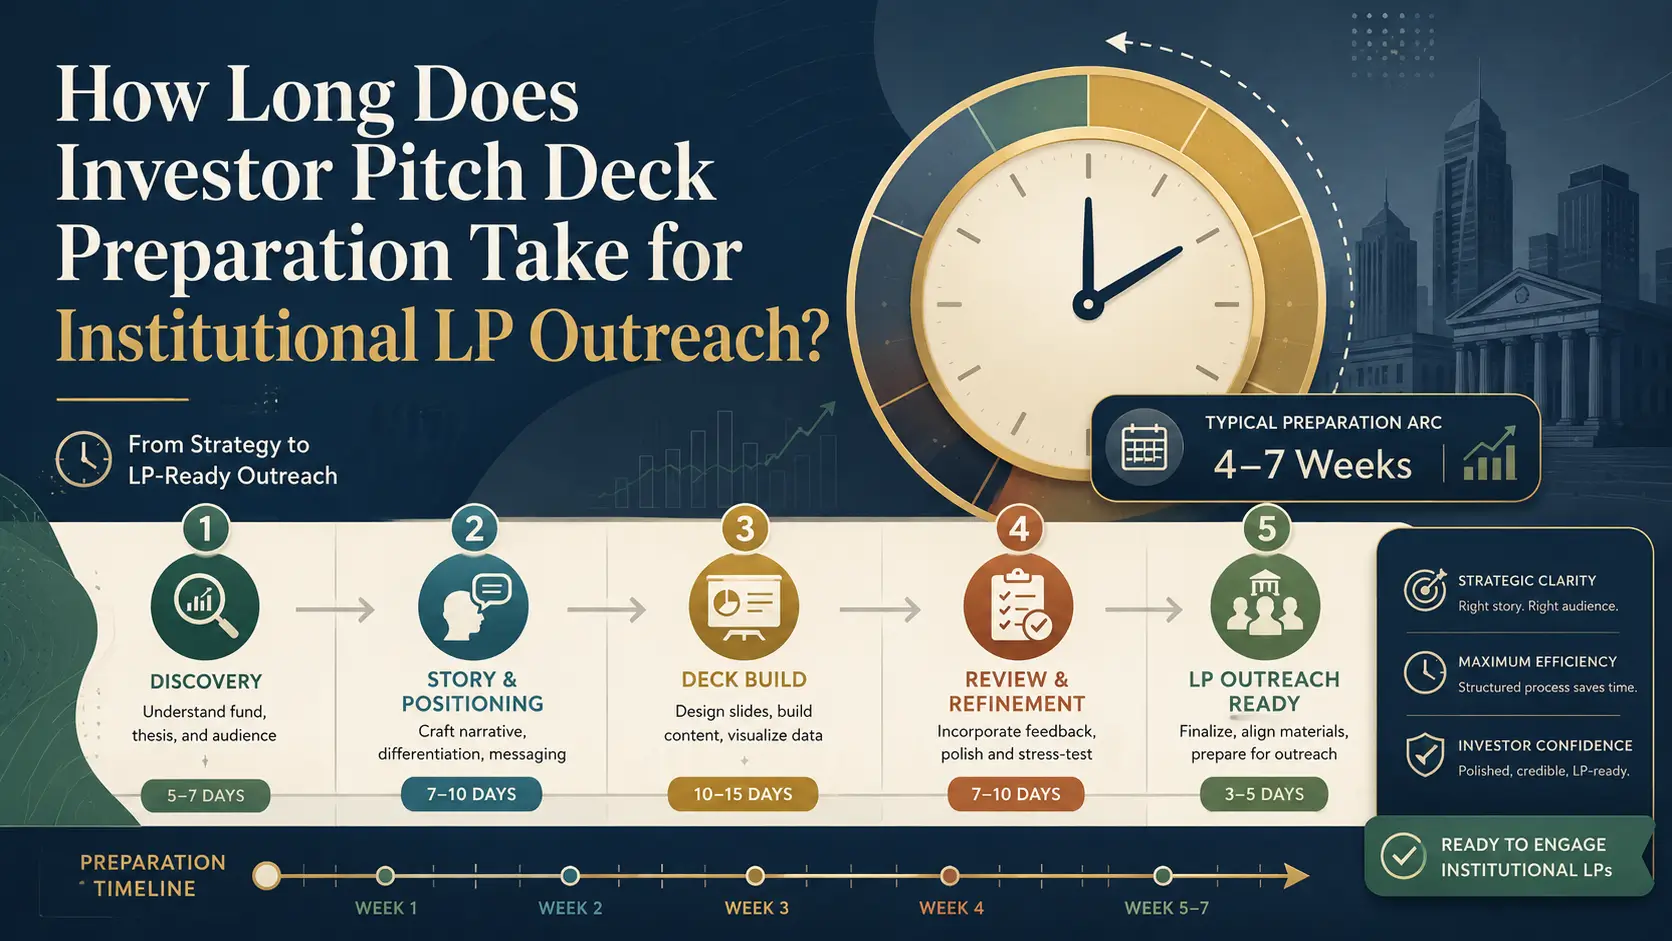
How Long Does Investor Pitch Deck Preparation Take for Institutional LP Outreach?
Disclosure
Nothing on this site constitutes an offer to sell, or a solicitation of an offer to purchase, any security under the Securities Act of 1933, as amended, or any applicable state securities laws. Any offering of securities is made only by means of a formal private placement memorandum or other authorized offering documents delivered to qualified investors.
IRC Partners is a capital advisory firm. IRC Partners is not a registered investment adviser under the Investment Advisers Act of 1940 and does not provide investment advice as defined thereunder.
Certain statements in this article may constitute forward-looking statements, including statements regarding market conditions, capital availability, investor demand, and transaction outcomes. Such statements reflect current assumptions and expectations only. Actual results may differ materially due to market conditions, regulatory developments, company-specific factors, and other variables. IRC Partners makes no representation that any outcome, return, or result described herein will be achieved.
References to prior mandates, transaction volume, network credentials, or capital raised are provided for illustrative purposes only and do not constitute a guarantee or prediction of future results. Past performance is not indicative of future outcomes. Individual results will vary. Network credentials and transaction statistics referenced on this site reflect the aggregate experience of IRC Partners' principals and affiliated advisors and are not a representation of assets managed or transactions closed solely by IRC Partners.
Certain data, statistics, and information presented in this article have been obtained from third-party sources. IRC Partners has not independently verified such information and expressly disclaims responsibility for its accuracy, completeness, or timeliness. Readers should independently verify any third-party data before relying on it.
Readers are strongly encouraged to consult qualified legal, financial, and tax professionals before making any investment, capital raising, or business decision.
Schedule A Meeting
You get one shot to raise the right way. If this raise is worth doing, it’s worth doing with precision, leverage, and control.
This isn’t a practice run. Serious capital. Serious strategy. Let’s raise it right.
We onboard a maximum of seven
new strategic partners each quarter, by application only, to maximize your chances of securing the capital you need.
