


How Should Founders Build a 24-Month Operating Plan For a Series B Growth Equity Raise?
How Should Founders Build a 24-Month Operating Plan For a Series B Growth Equity Raise?
A 24-month Series B operating plan should combine a bottoms-up revenue model, role-level headcount plan, milestone-based capital deployment schedule, and downside scenario. Together, these components show how revenue, hiring, capital use, and unit economics are expected to connect over the planning period.
The standard is systems thinking. The plan must show that the founder has modeled the business honestly, sequenced capital against milestones, and stress-tested the assumptions before an analyst does it for them.
This guide covers what growth equity investors look for inside the plan, the four components every institutional-grade plan must include, how to stress test the plan before diligence begins, and the threshold at which the plan signals readiness.
The Capital Raise Pre-Flight is IRC Partners' fixed-fee diagnostic that scores a raise against the same twelve institutional gates a deal must clear before IRC Partners takes it into a strategic partnership.
What Growth Equity Investors Read in a 24-Month Operating Plan
Growth equity investors use the operating plan to answer four questions in the first pass. Each question maps to a structural element of the plan, and a missing element is a missing answer.
The Four Questions Analysts Ask First
1. Does the headcount plan drive the revenue model? Bessemer Venture Partners tracks revenue per full-time employee as a core efficiency metric for growth-stage SaaS companies. A plan where headcount additions carry no traceable connection to revenue output through sales capacity, customer success ratios, or engineering throughput reads as a budget document. Analysts expect to see each hire class mapped to a revenue or retention outcome within the 24-month window.
2. Is the capital deployment sequenced to milestones? Institutional investors read the use-of-funds as a milestone map. A plan that deploys capital in equal monthly tranches, with milestone logic absent, tells the analyst that the founder has skipped the question of what this round is supposed to prove before the next one.
3. Do the unit economics hold at the plan's exit ARR? The plan must show that the business becomes more efficient as it scales. According to Bessemer's State of the Cloud 2023, top-quartile B2B SaaS companies at the Series B stage carry a CAC payback period under 12 months, median performers fall between 15 and 24 months, and anything above 36 months is flagged as inefficient by Bessemer's growth-stage benchmarks. A 24-month plan that projects scale and leaves CAC payback flat or widening will be flagged.
4. What does the downside case look like? A plan with only an upside scenario signals that the business model has been built to impress, and analysts identify that construction immediately. Bessemer's diligence framework expects a downside case that reduces revenue assumptions by 20 to 30 percent and shows the business still reaching a defensible next milestone. A plan carrying only an upside scenario signals overconfidence and a model the founder has left unexamined under pressure.
Founders preparing a Series B growth equity raise should treat these four questions as the minimum standard before the plan enters the data room.
The Four Components Every Institutional-Grade Operating Plan Must Include
An institutional-grade 24-month operating plan has four components. Each one serves a specific function in the diligence process, and each one is read by a different member of the investment team.
Component 1: A Bottoms-Up Revenue Model
The revenue model must be built from the ground up, starting with sales capacity. Bessemer Venture Partners defines sales efficiency benchmarks that require founders to show how many quota-carrying reps the business can support, what the average ramp time is, and what quota attainment looks like at full productivity. Analysts trace the revenue line back to its inputs, and a model that cannot be traced fails the construction test.
The bottoms-up model should show:
- Quota-carrying headcount by quarter, with ramp schedules
- Average contract value and net revenue retention assumptions
- New logo targets per quarter, with a conversion rate from pipeline
- Expansion revenue as a separate line, tied to customer success capacity
Component 2: A Headcount Plan with Role-Level Attribution
Every hire in the 24-month window must be tied to a specific output. Bessemer's efficiency benchmarks for growth-stage SaaS companies show that the top quartile maintains revenue per employee ratios that require discipline in hiring sequencing. A plan that adds headcount in every department simultaneously tells the analyst that hiring sequencing has received no discipline, and the output logic behind each role has been left unresolved.
The headcount plan should show the role, the hire date, the output the role is expected to generate within 90 days, and the revenue or retention impact within the 24-month window. Engineering and product headcount should tie to specific feature delivery milestones that support the revenue model.
Component 3: A Capital Deployment Schedule Tied to ARR Milestones
Institutional investors read the capital deployment schedule as a sequencing test. Bessemer's framework for growth-stage companies ties each capital tranche to a specific ARR threshold. A plan that shows capital deployed over 24 months without naming the ARR milestone each tranche is designed to reach tells the analyst that the founder has not identified what the round is supposed to prove.
The deployment schedule should name the milestone each tranche funds, the timeline from deployment to milestone, and the contingency if the milestone is delayed. Founders who have worked through how growth equity investors calculate CAC payback for a Series B SaaS company will recognize that a model without milestone sequencing is the most common construction failure in growth-stage plans.
Component 4: A Downside Scenario with a Defensible Floor
The downside scenario is the component most founders skip and the one analysts weigh most heavily. Bessemer's diligence process applies a revenue reduction of 20 to 30 percent to the base case and evaluates whether the business still reaches a defensible milestone. A plan where the downside scenario shows strong growth will be flagged as constructed to pass a review. Analysts apply the stress reduction to surface the real floor, and a plan that cannot show one fails the component test.
The downside scenario must show the ARR floor the business reaches if revenue assumptions miss by 25 percent, the burn rate at that floor, the runway remaining, and the specific actions management would take to preserve the milestone. A downside case that reduces revenue while holding headcount and burn flat leaves the operational response unaddressed, and analysts read that gap as a construction failure.
Key structural standard: Bessemer Venture Partners benchmarks show that a 24-month operating plan with all four components in place, each traceable to a specific assumption, passes the financial model gate in institutional diligence. A plan missing any one component fails the gate regardless of the headline revenue projection.
How to Stress Test the Plan Before Diligence Begins
A stress test run by the founder before the data room opens is worth more than a revision requested during diligence. The goal is to surface the assumptions that break first under pressure, so the plan can be rebuilt around defensible inputs before the data room opens.
The Three Stress Tests Institutional Analysts Run
Stress Test 1: The Sales Capacity Reduction. Reduce the number of productive quota-carrying reps by 30 percent in months seven through twelve. Bessemer Venture Partners benchmarks show that sales ramp periods for B2B SaaS companies typically run four to six months before a rep reaches full productivity. A plan that assumes full productivity from month one in every hire cohort will fail this test. The question is whether the revenue model still reaches its 24-month ARR target with a realistic ramp assumption applied.
Stress Test 2: The Net Revenue Retention Floor. Reduce net revenue retention by 10 percentage points from the base case assumption. Bessemer's efficiency metrics for growth-stage SaaS companies show that net revenue retention is the single most powerful lever in a 24-month model because it compounds in both directions. A plan that assumes 120 percent net revenue retention without modeling the impact of a drop to 110 percent is a plan that has not been honestly tested. The stress test should show whether the business reaches its next ARR milestone under the reduced retention assumption, and what the burn impact is.
Stress Test 3: The Hiring Delay. Delay every planned hire by 60 days across the full 24-month window. Bessemer's research on growth-stage operating plans shows that hiring delays are among the most common execution risks in the first 12 months after a growth equity close. A plan that depends on all hires arriving on schedule, with no contingency for a delayed VP of Sales or a slow engineering search, signals execution fragility. The stress test should show the revenue and milestone impact of a uniform 60-day hiring delay and the specific actions management would take to offset it.
What a Plan That Passes the Stress Test Looks Like
A plan that passes all three stress tests shares three characteristics:
{{main-cta}}
The Threshold at Which the Operating Plan Signals Institutional Readiness
Institutional readiness is a specific standard, and the operating plan either meets it or it does not. The threshold has three markers, each of which analysts evaluate independently.
Marker 1: The Plan Survives a Bottoms-Up Reconstruction
An analyst should be able to rebuild the revenue model from its inputs without asking the founder any clarifying questions. Bessemer Venture Partners benchmarks the construction standard for growth-stage financial models against the ability to trace every revenue dollar to a specific sales rep, contract, or expansion event. A model that requires founder explanation generates follow-up questions during diligence, and follow-up questions extend timelines.
Marker 2: The Efficiency Metrics Improve Over the 24-Month Window
The plan must show that the business becomes more capital-efficient as it deploys the Series B proceeds. Bessemer's State of the Cloud research shows that growth-stage companies with improving efficiency metrics, specifically a CAC payback period trending from the 15 to 24 month median range toward the under 12 month top-quartile threshold, are the ones that generate competitive term sheets. A plan that holds efficiency flat or shows it declining as revenue scales will be read as a sign that the growth model has not been proven at the target ARR.
Marker 3: The Plan Connects to the Next Raise
A 24-month operating plan that ends at a specific ARR milestone without showing how that milestone positions the company for the next capital event is an incomplete plan. Bessemer's framework for growth-stage companies requires that the operating plan demonstrate a clear path from the Series B close to the metrics required for a Series C or a path to profitability. A plan that ends at month 24 with no named next milestone tells the analyst that the founder has skipped the full capital formation strategy.
Founders who have completed the structural work on their operating plan and want an independent read on whether it passes the institutional standard should review the 10 mistakes that kill an institutional raise before the data room opens.
The operating plan is the diligence. Growth equity investors use the operating plan to decide whether to invest. A plan that signals systems thinking passes. A plan that signals projection optimism does not advance.
Frequently Asked Questions
What time horizon should a 24-month operating plan cover for a Series B?
The plan should cover exactly 24 months from the anticipated close date of the Series B, ending at a named ARR milestone. Bessemer Venture Partners benchmarks growth-stage plans against specific ARR thresholds, and a plan that ends without naming the exit ARR and the next capital event milestone will be read as structurally incomplete by institutional analysts.
How granular does the headcount plan need to be for institutional diligence?
Institutional analysts expect role-level attribution, meaning each hire is named by function, hire date, expected ramp period, and the specific revenue or retention output the role is designed to generate. Bessemer's efficiency benchmarks for growth-stage SaaS companies require that revenue per employee ratios remain defensible as headcount scales, and a plan without role-level detail cannot demonstrate that discipline.
What CAC payback period should the plan target to pass institutional review?
According to Bessemer Venture Partners, a CAC payback period under 12 months represents top-quartile performance at the Series B stage. The median range runs from 15 to 24 months. A plan projecting CAC payback above 36 months will be flagged as inefficient by Bessemer's growth-stage benchmarks.
How many scenarios should the operating plan include?
The plan should include a base case and a downside case at minimum. Bessemer's diligence framework applies a revenue reduction of 20 to 30 percent to the base case and evaluates whether the business still reaches a defensible milestone. A plan with only an upside scenario will be flagged as optimistic. An optional upside case can be included, but analysts focus their scrutiny on the downside.
What is the most common structural failure in a 24-month operating plan?
The most common failure is a top-down revenue model with no bottoms-up sales capacity logic. Bessemer Venture Partners identifies the inability to trace revenue dollars back to specific reps, contracts, or expansion events as the primary construction failure in growth-stage financial models. A model that starts with a market size and works backward to a revenue figure fails the financial model gate before any other assumption is evaluated.
How should the capital deployment schedule be structured in the plan?
The capital deployment schedule should tie each tranche of proceeds to a specific ARR milestone, with a named timeline from deployment to milestone and a contingency for delay. Bessemer's framework for growth-stage companies requires that the use of funds demonstrate what the round is designed to prove before the next capital event. A schedule that deploys capital in equal monthly tranches with no milestone logic signals that the founder has not identified the strategic purpose of the raise.
At what ARR should a founder begin building the 24-month operating plan for a Series B?
Founders at $10M to $15M ARR should begin building the institutional-grade operating plan 12 to 18 months before the anticipated Series B close. Bessemer Venture Partners notes that institutional capital formation commonly requires a lead time of 12 to 18 months, and a plan built at the start of the raise process will carry assumptions that have not been tested against actual operating data. Building the plan early allows the business to validate or revise its core assumptions before diligence begins.
Continue reading this series:
- How to Raise Capital in 2026 for Your Series A Round
- Series A Valuations: Calculate Your Raise in 2026
- What Do Series B Growth Equity Investors Look for in a Company?
The Capital Raise Pre-Flight is IRC Partners’ fixed-fee diagnostic that scores a raise against the same twelve institutional gates a deal must clear before IRC Partners takes it into a strategic partnership. It is where every engagement begins, whether you are pre-revenue building toward a first institutional round or scaling a company that has raised before. For deals that clear, the full strategic partnership follows. IRC Partners advises operators raising $5M to $250M of institutional capital. If you are taking a raise to market, start here.
Need guidance on your capital raise?


How Should a Startup Document Investor Default Remedies in a Multi-Close Bridge Financing?

Secure Better Info Rights Terms in Growth Capital Raises
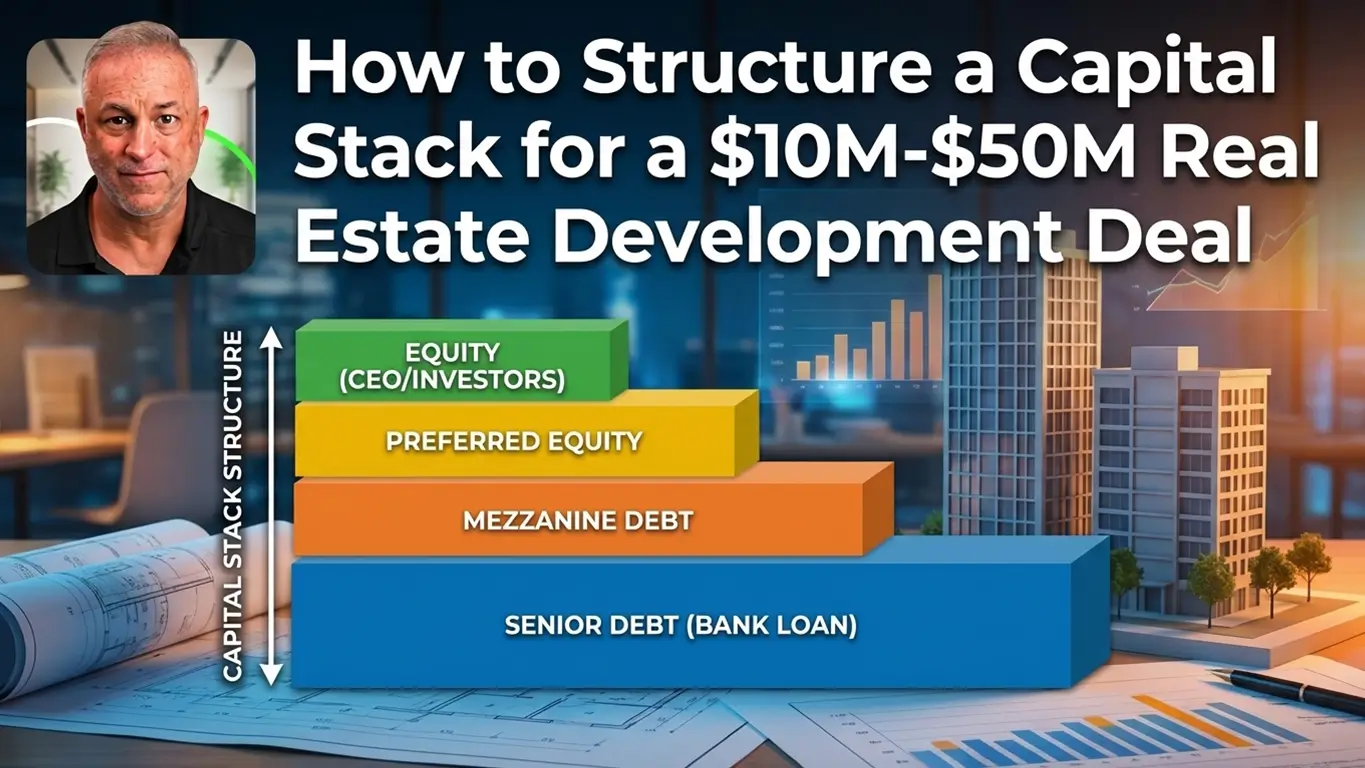
How Seasoned Real Estate Developers Access Institutional Allocators: The Warm Introduction Framework for $10M+ Raises
Disclosure
Nothing on this site constitutes an offer to sell, or a solicitation of an offer to purchase, any security under the Securities Act of 1933, as amended, or any applicable state securities laws. Any offering of securities is made only by means of a formal private placement memorandum or other authorized offering documents delivered to qualified investors.
IRC Partners is a capital advisory firm. IRC Partners is not a registered investment adviser under the Investment Advisers Act of 1940 and does not provide investment advice as defined thereunder.
Certain statements in this article may constitute forward-looking statements, including statements regarding market conditions, capital availability, investor demand, and transaction outcomes. Such statements reflect current assumptions and expectations only. Actual results may differ materially due to market conditions, regulatory developments, company-specific factors, and other variables. IRC Partners makes no representation that any outcome, return, or result described herein will be achieved.
References to prior mandates, transaction volume, network credentials, or capital raised are provided for illustrative purposes only and do not constitute a guarantee or prediction of future results. Past performance is not indicative of future outcomes. Individual results will vary. Network credentials and transaction statistics referenced on this site reflect the aggregate experience of IRC Partners' principals and affiliated advisors and are not a representation of assets managed or transactions closed solely by IRC Partners.
Certain data, statistics, and information presented in this article have been obtained from third-party sources. IRC Partners has not independently verified such information and expressly disclaims responsibility for its accuracy, completeness, or timeliness. Readers should independently verify any third-party data before relying on it.
Readers are strongly encouraged to consult qualified legal, financial, and tax professionals before making any investment, capital raising, or business decision.
Schedule A Meeting
You get one shot to raise the right way. If this raise is worth doing, it’s worth doing with precision, leverage, and control.
This isn’t a practice run. Serious capital. Serious strategy. Let’s raise it right.
We onboard a maximum of seven
new strategic partners each quarter, by application only, to maximize your chances of securing the capital you need.
