


What Should a Hold-Period Model Include for a Real Estate Development Project?
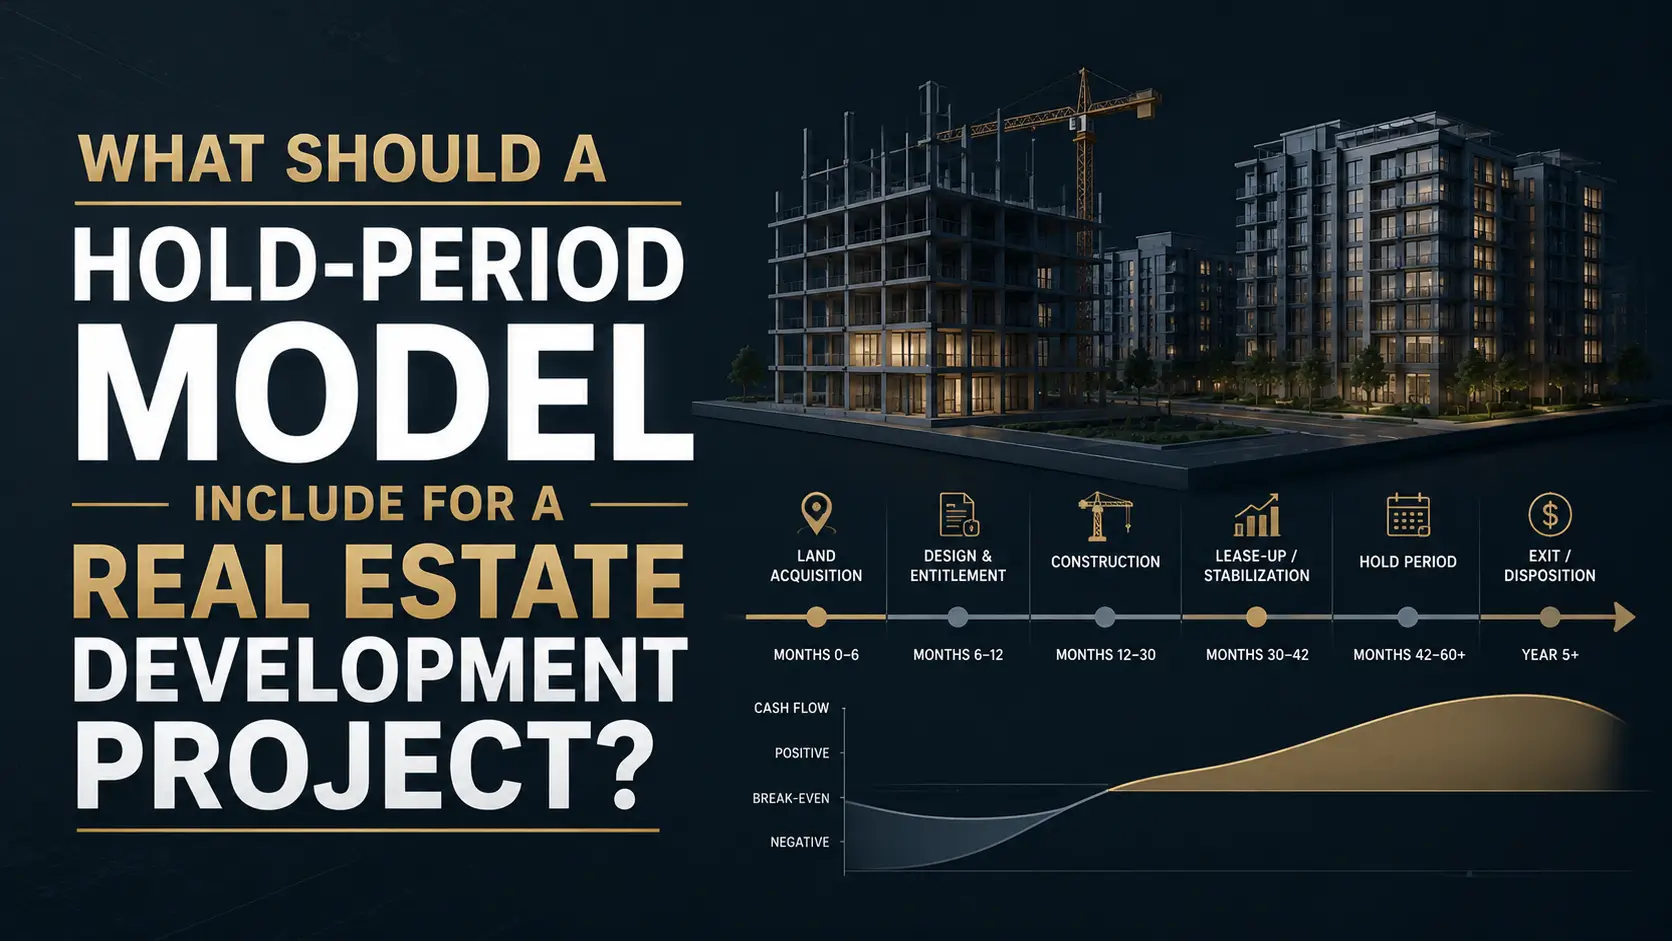
TL;DR: Build a real estate development hold-period model that traces asset performance from completion and lease-up through refinance and exit.
- Minimum Hold-Period Model Components for an Institutional-Grade Development Deal: An institutional-grade hold-period model for a development project must cover each of the following components.
- Completion and Lease-Up Period: The First Section LPs Pressure-Test: The lease-up period is where LP scrutiny is sharpest in 2026.
- Stabilized Operations Period: How the Model Converts Occupancy Into Durable NOI: Once the asset reaches stabilization, the hold-period model must carry revenue, operating expenses, reserves, and debt service through the full remaining hold.
A real estate development model can lose institutional LP confidence when it shows stabilized returns without proving how the asset reaches them. If the model does not trace construction completion, lease-up, operating cash flow, debt service, refinance eligibility, and exit proceeds period by period, investors cannot verify whether projected returns come from asset performance or optimistic assumptions. A hold-period model solves this by mapping the full path from completion through stabilization, any recapitalization event, and final disposition, with each cash flow tied to the underlying model tabs and supporting schedules.
This piece is part of a series on building institutional-grade financial models for real estate capital raises. The broader framework for what belongs in the full investor-ready package is covered in what an investor-ready materials package for a real estate sponsor must include. The specific tabs that feed the hold-period model are addressed in what financial model tabs a real estate sponsor should prepare before institutional LP outreach.
In 2026, LP underwriting standards have tightened around the period between construction closeout and exit. Reviewers are spending more time on lease-up assumptions, refinance eligibility logic, and exit cap rate support than they were two or three years ago. A hold-period model that cannot show how the asset transitions from construction completion to investor distributions will create diligence friction before a single investment committee discussion begins.
Minimum Hold-Period Model Components for an Institutional-Grade Development Deal
An institutional-grade hold-period model for a development project must cover each of the following components. Each one should run period by period rather than appear as a single aggregate figure.
The transition points matter as much as the assumptions. The model should clearly mark when the project moves from construction to lease-up, when it reaches stabilization, when a refinance event occurs if applicable, and when the disposition takes place. LPs use those transition points to verify that return timing is grounded in asset performance rather than a fixed schedule.
Return outputs must reflect the actual timing of cash flows at each period. A model that shows a blended IRR without showing the cash flow sequence that produces it will not survive first-pass institutional review.
Completion and Lease-Up Period: The First Section LPs Pressure-Test
The lease-up period is where LP scrutiny is sharpest in 2026. Delayed absorption changes refinance eligibility, pushes exit timing, and compresses LP returns faster than almost any other variable. A model that treats lease-up as a flat occupancy ramp with no cash flow detail will be flagged immediately.
What the Model Must Show During Lease-Up
- Construction completion and CO milestone. State the expected completion date and the certificate of occupancy date as separate line items. Phased delivery should show each phase separately, with its own absorption schedule.
- Unit or space absorption by period. Show how many units or square feet are leased each month or quarter. The ramp should reflect market demand evidence and submarket absorption data, not a straight-line plug.
- Revenue impact of concessions and downtime. Model free rent periods, lease-up concessions, credit loss, and vacancy by period. These are real cash flow items during lease-up and they affect reserve draws, debt coverage, and the date the asset reaches stabilization.
- Ramping operating costs. Expenses do not begin at stabilized levels on day one. The model should show how operating costs build as occupancy grows.
- Stabilization date. Define stabilization as a specific occupancy threshold, typically 90 to 95 percent, and show the period in which the asset crosses that line.
Why This Section Has Become More Sensitive
Institutional LPs are more conservative about lease-up timing assumptions in 2026 because slower absorption directly affects refinance eligibility. If the model assumes stabilization in month eight but the market supports month twelve, the refinance window and the LP distribution timeline both shift. A lease-up schedule grounded in submarket absorption data, with a conservative ramp, is a diligence advantage.
Stabilized Operations Period: How the Model Converts Occupancy Into Durable NOI
Once the asset reaches stabilization, the hold-period model must carry revenue, operating expenses, reserves, and debt service through the full remaining hold. Stabilized NOI should appear as a period-based result, not a single line item detached from the monthly or quarterly build.
LPs look at the stabilized operations section to answer three questions:
- Does the NOI build support the debt coverage ratio the model claims?
- Are expense growth and replacement reserves underwritten conservatively enough to support distributions?
- Does the operating performance justify the exit value the model projects?
What the Stabilized Operations Section Must Include
- Revenue by period. Gross potential rent, vacancy allowance, concessions, credit loss, and effective gross income shown separately for each period.
- Operating expense detail. Line-item expenses with growth rates that reconcile to the assumptions tab or a supporting expense schedule. Management fees should be stated as a percentage of effective gross income, not a flat dollar assumption.
- Replacement reserve funding. The model should show reserve contributions by period. Reserves that appear in the assumptions tab but do not flow through the cash flow build are a reconciliation gap LPs will find.
- Debt service by period. Interest-only periods, amortization, and any balloon or maturity events should be shown as separate line items so the coverage ratio can be traced period by period.
Key tie-back: Every operating assumption in this section should reconcile to a named schedule or tab. If the expense growth rate is 3 percent annually, that rate should appear in the assumptions tab and flow forward consistently. Disconnected assumptions are one of the most common diligence friction points in development model reviews.
The stabilized operations section is also where the model establishes the NOI basis that will support the exit valuation. LPs will divide the projected exit price by the Year N+1 forward NOI to check the implied cap rate. If that implied cap rate does not match the stated exit cap, the model has a reconciliation problem.
Refinance or Recapitalization Logic: When Interim Capital Events Change the Return Story
If a refinance or recapitalization is part of the business plan, the hold-period model must show it as a modeled event, with timing tied to an operating threshold rather than a calendar date alone.
The Refinance Event Must Show
- Trigger condition. State what operating milestone triggers the refinance: DSCR coverage, stabilized occupancy, LTV eligibility, or a specific NOI threshold. A date-only assumption signals the sponsor has not tested whether the asset will actually qualify.
- Loan sizing logic. Show how the new loan amount is calculated. For agency or conventional permanent financing, this typically means applying a DSCR constraint and an LTV constraint and taking the lower of the two.
- Payoff of the construction loan. The model should show the construction loan balance at the refinance date, payoff costs, and any prepayment or exit fees.
- Net proceeds and distribution. Show what proceeds remain after payoff and fees, and how those proceeds flow to LPs and the GP under the waterfall.
- Impact on LP return metrics. A mid-hold refinance that returns capital to LPs changes the IRR profile of the investment. The model should show LP cash flows before and after the refinance event so the return impact is transparent.
The detail required to model a refinance event correctly is covered more fully in how to model a refinance or recapitalization event in a real estate development deal. The key point for the hold-period model is that a refinance assumption without an operating trigger is a red flag. LPs read it as a placeholder, and placeholders do not survive diligence.
Disposition Period and Sensitivity Analysis: Where Weak Assumptions Get Exposed Fastest
The disposition section is where the hold-period model is most exposed to LP scrutiny. Exit assumptions drive a large share of projected returns in development deals, and reviewers in 2026 are applying exit cap decompression buffers as a baseline, not an optional stress test.
The Disposition Section Must Show
- Sale timing. State the expected exit date and the hold period in years. The exit date should follow logically from the stabilization date and the business plan, not be set to optimize the IRR.
- Terminal value calculation. A defensible terminal value uses Year N+1 forward NOI divided by the exit cap rate, less disposition costs, which run roughly 2.5% to 3.5% of gross sale price at the institutional level. This follows the institutional terminal value convention used across CRE underwriting. The Year N+1 NOI should be traceable to the stabilized operations section of the model.
- Exit cap rate with decompression buffer. Institutional convention in 2026 calls for an exit cap rate that is 25 to 75 basis points above the current market going-in cap rate for the asset class and submarket, a range grounded in the going-in to exit cap spread mechanics that institutional underwriters apply across hold periods. A model that uses a flat going-in cap as the exit assumption will be questioned immediately.
- Gross sale price, disposition costs, and debt payoff. Show the full proceeds bridge: gross price minus disposition costs minus remaining loan balance equals net proceeds available for distribution.
- Net proceeds into the waterfall. The net proceeds from sale should flow directly into the waterfall tab and reconcile to LP and GP distributions.
Sensitivity Outputs LPs Expect to See
The hold-period model should stress-test at minimum four variables:
| Component | What It Must Show |
|---|---|
| Completion timing | Construction completion date, certificate of occupancy milestone, phased delivery if applicable |
| Lease-up ramp | Unit or space absorption by period, vacancy curve, and the date stabilization is reached |
| Stabilization assumptions | Occupancy threshold, stabilized revenue, and the basis for calling the asset stabilized |
| Operating cash flow by period | Revenue, operating expenses, reserves, and net operating income through the full hold period |
| Reserve treatment | Operating reserve draws during lease-up and replacement reserve funding post-stabilization |
| Debt service | Interest-only and amortization periods, maturity dates, and any extension assumptions |
| Stress Variable | Why LPs Test It |
|---|---|
| Hold duration (+1 to +2 years) | Tests whether extended holds compress or expand returns |
| Exit cap widening (+50 to +100 bps) | Tests sensitivity to cap rate movement at exit |
| Rent growth variance (-10% to -15%) | Tests whether NOI supports exit value under softer revenue |
| Lease-up delay (+2 to +4 months) | Tests refinance eligibility and LP distribution timing |
A downside case that still returns LP capital and covers the preferred return under these stress inputs is a model that will hold up in committee review. A model where a 50 basis point exit cap widening breaks the preferred return is a structural problem, not a presentation problem.
How the Hold-Period Model Ties Back to Core Tabs and What Weak Modeling Signals to an LP
The hold-period model does not stand alone. Every assumption in it should pull from a named tab or supporting schedule. When it does, LPs can trace the logic. When it does not, they flag it.
The Core Tie-Back Map
| Hold-Period Section | Source Tab or Schedule |
|---|---|
| Completion timing | Construction draw schedule and timeline tab |
| Lease-up ramp | Rent roll or lease-up schedule, market study |
| Operating expenses | Expense schedule or assumptions tab |
| Reserve funding | Reserve schedule, operating agreement |
| Debt service | Debt tab with loan terms and amortization |
| Refinance event | Debt tab, DSCR and LTV sizing logic |
| Disposition proceeds | Waterfall tab, sources and uses |
| Sensitivity outputs | Assumptions tab with scenario toggles |
Version control and consistent labeling matter here. A hold-period section that references assumptions from a tab named differently in the model creates reconciliation questions even when the math is right. Clear labels, consistent naming, and a model where every number can be traced back to its source are what institutional-grade means in practice.
For context on how fee income, promote economics, and GP participation flow through the hold-period model and into the waterfall, see how to model fee income, promote economics, and GP participation for investors. For the broader question of how waterfall economics are structured and defended, the framework for calculating the right GP/LP split for a real estate deal is directly relevant.
What a Weak or Missing Hold-Period Model Signals
A hold-period model that is incomplete, inconsistent, or missing key sections sends specific signals to an institutional LP during first-pass diligence:
- Missing lease-up detail signals the sponsor has not modeled the cash impact of the lease-up period and may not have tested refinance eligibility.
- Stabilized snapshot only signals the sponsor is presenting a best-case outcome rather than a period-by-period path to that outcome.
- Refinance assumption with no operating trigger signals the refinance is a return assumption, not a modeled event.
- Exit cap at or below going-in cap signals the sponsor is underwriting to a best-case exit without a decompression buffer.
- No sensitivity outputs signals the model has not been stress-tested and may break on modest assumption changes.
What This Looks Like in Practice
On a large ground-up multifamily development, a core part of the pre-outreach model review is restructuring the hold-period section to show the lease-up ramp, the stabilization trigger, the refinance sizing logic tied to DSCR and LTV thresholds, and the exit valuation tied to Year N+1 forward NOI. The revised model gives LP reviewers a traceable path from construction completion to investor distributions, with every operating assumption reconciled to the supporting schedules. That structure reduces diligence friction and supports productive committee conversations from the first submission.
What to Do If Your Hold-Period Model Is Incomplete Before Outreach
If the hold-period section of the model exists but is missing period-by-period detail, lacks tie-backs to supporting schedules, or carries assumptions that have not been stress-tested, the model is not ready for institutional LP review.
The path forward is to audit the model against the components listed above, identify which sections are missing or inconsistent, and rebuild those sections before any outreach begins. Structural model problems discovered mid-process add time and reduce LP confidence. Fixing them before outreach is a structural advantage.
Frequently Asked Questions
How long should the hold period be in a real estate development model?
The hold period in a development model should reflect the actual business plan: the time from construction completion through stabilization, any refinance or recapitalization event, and the projected exit. For ground-up multifamily deals, this typically runs three to seven years from completion. The model should test hold duration in the sensitivity analysis because extended holds affect LP return timing and exit cap assumptions.
What is the correct way to calculate terminal value in a development hold-period model?
Terminal value in a development hold-period model is calculated as Year N+1 forward NOI divided by the exit cap rate, less disposition costs. Year N+1 NOI should be pulled from the stabilized operations section of the model and must reconcile to the operating assumptions tab. Using the final stabilized year NOI rather than a forward year NOI understates the cap rate implied by the exit price and is a common diligence flag.
What exit cap rate decompression buffer do institutional LPs expect in 2026?
Institutional convention in 2026 calls for an exit cap rate that is 25 to 75 basis points above the current going-in cap rate for the asset class and submarket. A model that exits at or below the going-in cap signals the sponsor is underwriting to a best-case scenario. LPs will apply their own decompression buffer when stress-testing the model, so building it in from the start is a diligence advantage.
When should a refinance event appear in the hold-period model?
A refinance event should appear in the hold-period model when permanent financing or recapitalization is part of the business plan. The timing must be tied to an operating threshold, such as stabilized occupancy, DSCR coverage, or LTV eligibility, rather than a calendar date alone. A date-only refinance assumption signals the sponsor has not tested whether the asset will qualify for the financing the model assumes.
How many sensitivity scenarios does an institutional LP expect to see in a development model?
Institutional LPs expect at minimum four sensitivity scenarios in a development hold-period model: hold duration extension, exit cap rate widening, rent growth reduction, and lease-up delay. Each scenario should run through the full model and show the impact on LP IRR, equity multiple, and preferred return coverage. A sensitivity table that only adjusts one variable without flowing through to LP return metrics is treated as cosmetic.
What does a missing hold-period model signal to an LP during first-pass diligence?
A missing or incomplete hold-period model signals that the sponsor has not underwritten the operating path between construction completion and exit. LPs read it as evidence that projected returns may be supported by assumption risk rather than modeled asset performance. In 2026, this is one of the fastest ways to create diligence friction before a first LP call, because reviewers expect to see the full lifecycle model before engaging seriously.
How often should a real estate development hold-period model be updated before LP outreach?
A real estate development hold-period model should be updated any time a material assumption changes: construction timeline, lease-up velocity, financing terms, or exit cap rate benchmarks. Before outreach begins, the model should reflect current market data and should have been stress-tested within the prior 60 days. Sending a model with stale assumptions, particularly on lease-up timing or exit cap rates, is a credibility risk that is easy to avoid.
Continue reading this series:
- How should construction draws be presented in a real estate development financial model
- How should a real estate sponsor package project-level financials for LP committee review
- What documents should support a real estate financial model in an investor data room
IRC Partners advises operators raising $5M to $250M of institutional capital on structure, positioning, and round architecture. We take seven strategic partners per quarter. No placement agent model. No success-only theater. Institutional capital follows a deal built to institutional standard. If you want your current raise reviewed before it reaches the market and silently fails, apply here.
Need guidance on your capital raise?


Reviews of Investor Pitch Deck Preparation Advisors
What Happens If a Convertible Noteholder Cannot Be Located When the Company Needs an Amendment or Conversion Consent?
What Should My Investment Committee Deck Include?
Disclosure
Nothing on this site constitutes an offer to sell, or a solicitation of an offer to purchase, any security under the Securities Act of 1933, as amended, or any applicable state securities laws. Any offering of securities is made only by means of a formal private placement memorandum or other authorized offering documents delivered to qualified investors.
IRC Partners is a capital advisory firm. IRC Partners is not a registered investment adviser under the Investment Advisers Act of 1940 and does not provide investment advice as defined thereunder.
Certain statements in this article may constitute forward-looking statements, including statements regarding market conditions, capital availability, investor demand, and transaction outcomes. Such statements reflect current assumptions and expectations only. Actual results may differ materially due to market conditions, regulatory developments, company-specific factors, and other variables. IRC Partners makes no representation that any outcome, return, or result described herein will be achieved.
References to prior mandates, transaction volume, network credentials, or capital raised are provided for illustrative purposes only and do not constitute a guarantee or prediction of future results. Past performance is not indicative of future outcomes. Individual results will vary. Network credentials and transaction statistics referenced on this site reflect the aggregate experience of IRC Partners' principals and affiliated advisors and are not a representation of assets managed or transactions closed solely by IRC Partners.
Certain data, statistics, and information presented in this article have been obtained from third-party sources. IRC Partners has not independently verified such information and expressly disclaims responsibility for its accuracy, completeness, or timeliness. Readers should independently verify any third-party data before relying on it.
Readers are strongly encouraged to consult qualified legal, financial, and tax professionals before making any investment, capital raising, or business decision.
Schedule A Meeting
You get one shot to raise the right way. If this raise is worth doing, it’s worth doing with precision, leverage, and control.
This isn’t a practice run. Serious capital. Serious strategy. Let’s raise it right.
We onboard a maximum of seven
new strategic partners each quarter, by application only, to maximize your chances of securing the capital you need.
